Warren Buffett said it best: "Be fearful when others are greedy, and greedy when others are fearful."
He was talking about stocks, but the same instinct applies to the housing market right now. So let's have an honest conversation.
First, the Part You Won't Hear From Most Agents
There's no perfect time to buy a home. Nobody can call the bottom of the market, me included. Anyone who tells you they can is guessing.
The right time to buy is when it's right for you and your family. That means your job is stable, your savings are where they need to be, and you're ready to put down roots. Don't try to time the market. You'll drive yourself crazy, and you'll probably get it wrong.
Now the Hard Truth
If you're ready (finances in order, pre-approved, clear on what you want) and you're holding back only because the headlines make you nervous, frankly, that's the wrong move.
Buyers have more leverage right now than they've had in years, and the numbers back that up.
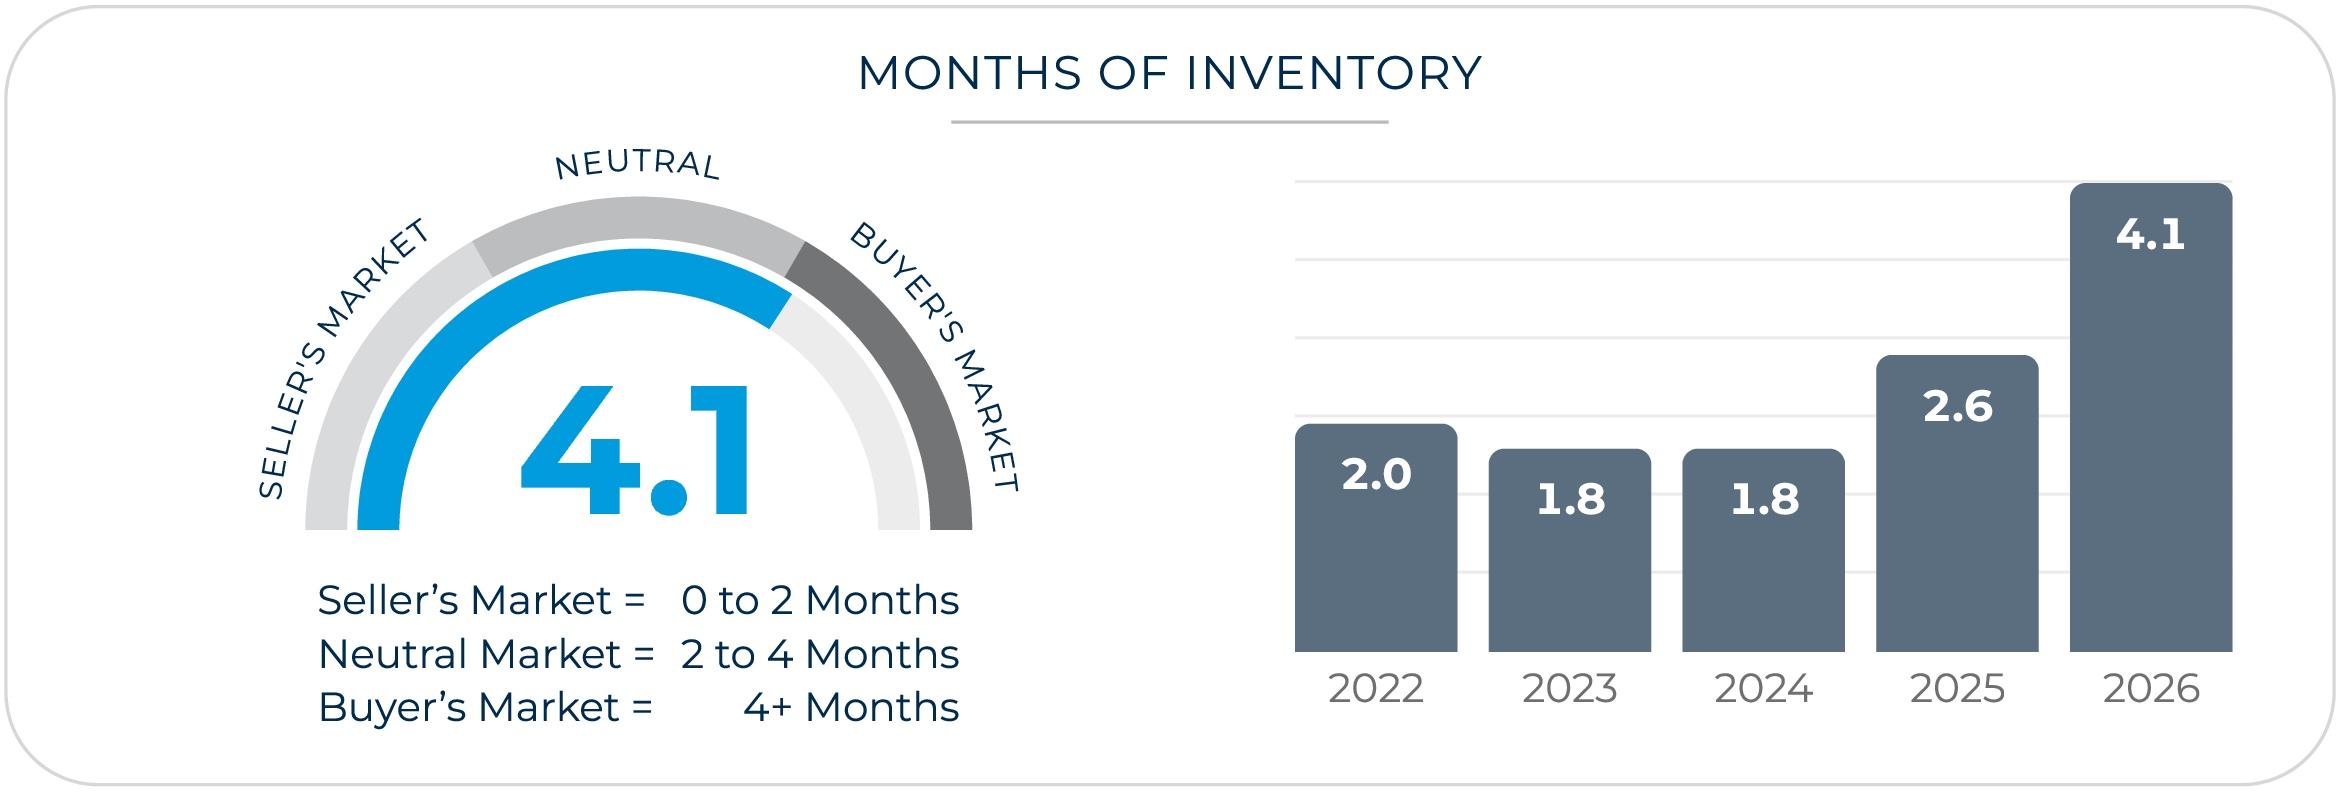
King County is at 4.1 months of inventory. That means if no new homes were listed, it would take over four months to sell everything on the market. A couple of years ago, that number was often under one month. And 48% of King County homes needed a price cut or a relist before they sold, and those homes averaged 94 days on market. Sellers are negotiating, and they're feeling the pressure.
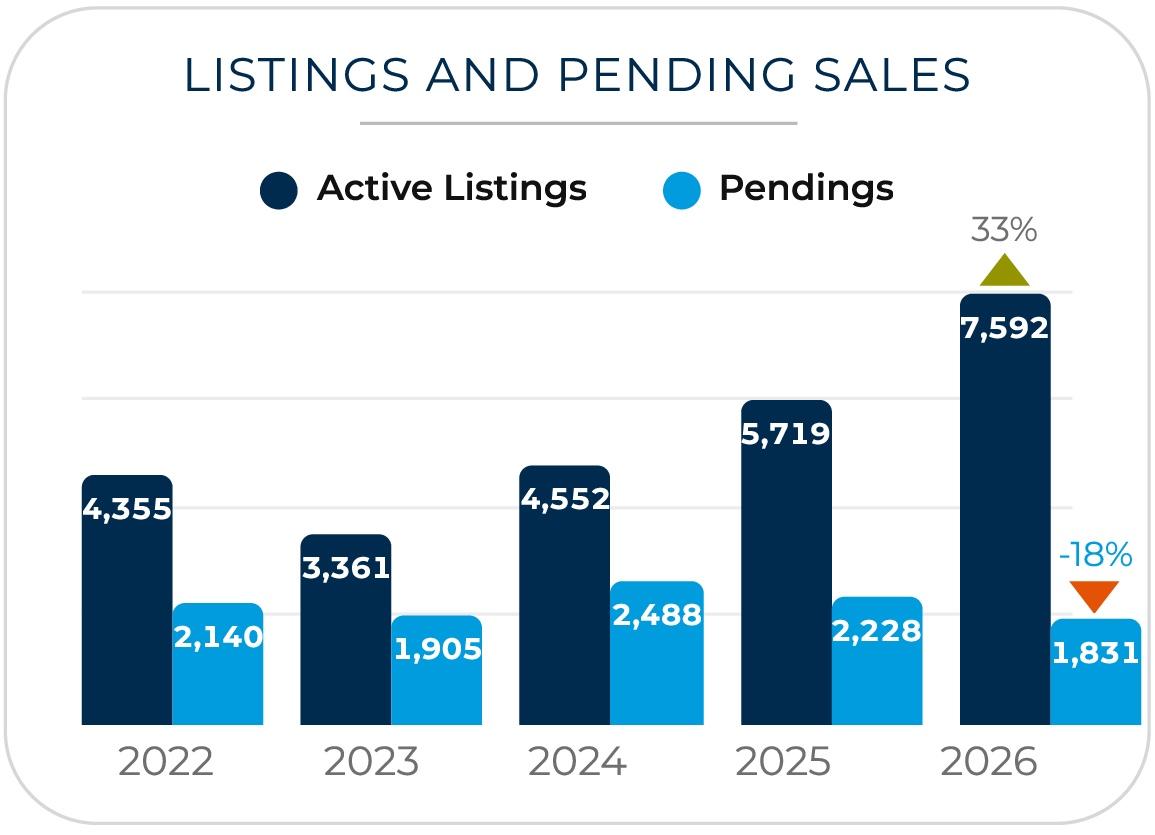
Buyers have more to choose from and less competition for it. Active listings in King County are up 33% from a year ago, to 7,592, while pending sales are down 18%, to 1,831.
What I'm seeing in real transactions:
- 01Offers below asking price are getting accepted. Not occasionally, regularly.
- 02Sellers are paying buyers' closing costs. That can mean thousands of dollars you keep.
- 03Sellers are funding interest rate buydowns, which lower your monthly payment for the first years of the loan.
- 04Terms are bending in your favor. Inspection contingencies, flexible closing dates, repair credits. These are all on the table again.
What a Seller-Paid 2-1 Buydown Is Worth
Say you borrow $600,000 at today's average rate of 7.11%. Your principal and interest payment is about $4,036 a month. With a seller-paid 2-1 buydown, your rate is 5.11% in year one and 6.11% in year two.
| Loan year | Rate | Monthly payment | You save |
|---|---|---|---|
| Year 1 | 5.11% | $3,261 | $775/month |
| Year 2 | 6.11% | $3,640 | $396/month |
| Year 3 on | 7.11% | $4,036 | — |
That's roughly $14,000 back in your pocket over two years, paid for by the seller. And with rates down four weeks in a row, you may be able to refinance down the road.
Payments are principal and interest only, on a 30-year fixed loan, and exclude taxes, insurance and HOA dues. The 7.11% rate is Freddie Mac's weekly average for November 12, 2026. Your lender can give you exact figures.
A couple of years ago, buyers waived inspections and went $50K over asking just to get a seller to answer the phone. Today the seller is the one wondering if anyone will call. That's a big change, and it won't last forever.
When the headlines settle down and buyers come back, this leverage goes away. The people who act while others are on the sidelines are the ones who get the deals.
Don't Overlook Condos
If a condo fits your lifestyle, now is a particularly good time to look. Condo buyers have the most leverage of anyone right now. King County condo inventory is at 6.2 months, active condo listings are up 22% from a year ago, and the median condo price is $465,000, down 15% from last year. For a buyer with 20% down at today's rates, a seller-paid 2-1 buydown on a typical condo would cut the payment by about $480 a month in year one.
Condos with well-run HOAs are some of the best opportunities out there. When you're touring, check for:
- 01A healthy reserve fund
- 02A recent reserve study
- 03No pending special assessments
- 04Reasonable dues for what they cover
- 05A low percentage of owners behind on dues
A well-managed building is an asset. I'm happy to help you dig into the HOA documents so you know exactly what you're buying, and my guide to buying a Seattle condo and reading the resale certificate walks through what to look for.
If You're Ready, Act. Don't Pause.
To sum up: if you're not ready, that's okay. Let's put together a plan so you will be. But if you are ready and fear is the only thing stopping you, I'd ask you to look at the facts instead of the headlines. The opportunity is real, and it's right now.
Sellers, This One's for You
Here's what the leverage I just described means for you: you have to stand out.
With 4.1 months of inventory, buyers have choices, and they're taking their time. The most important thing you can do is price your home to draw as many eyes as possible in the first week.
The numbers show what happens when you don't: nearly half of King County homes needed a price cut or a relist before they sold, and those homes averaged 94 days on market. That's three months of mortgage payments, utilities and stress, and in the end you usually sell for less than you would have by pricing it right from the start.
The longer a home sits, the bigger the discount. In October, King County homes that sold within 15 days went for their asking price on average. Homes on the market 91 days or more sold for 13.4% below it.
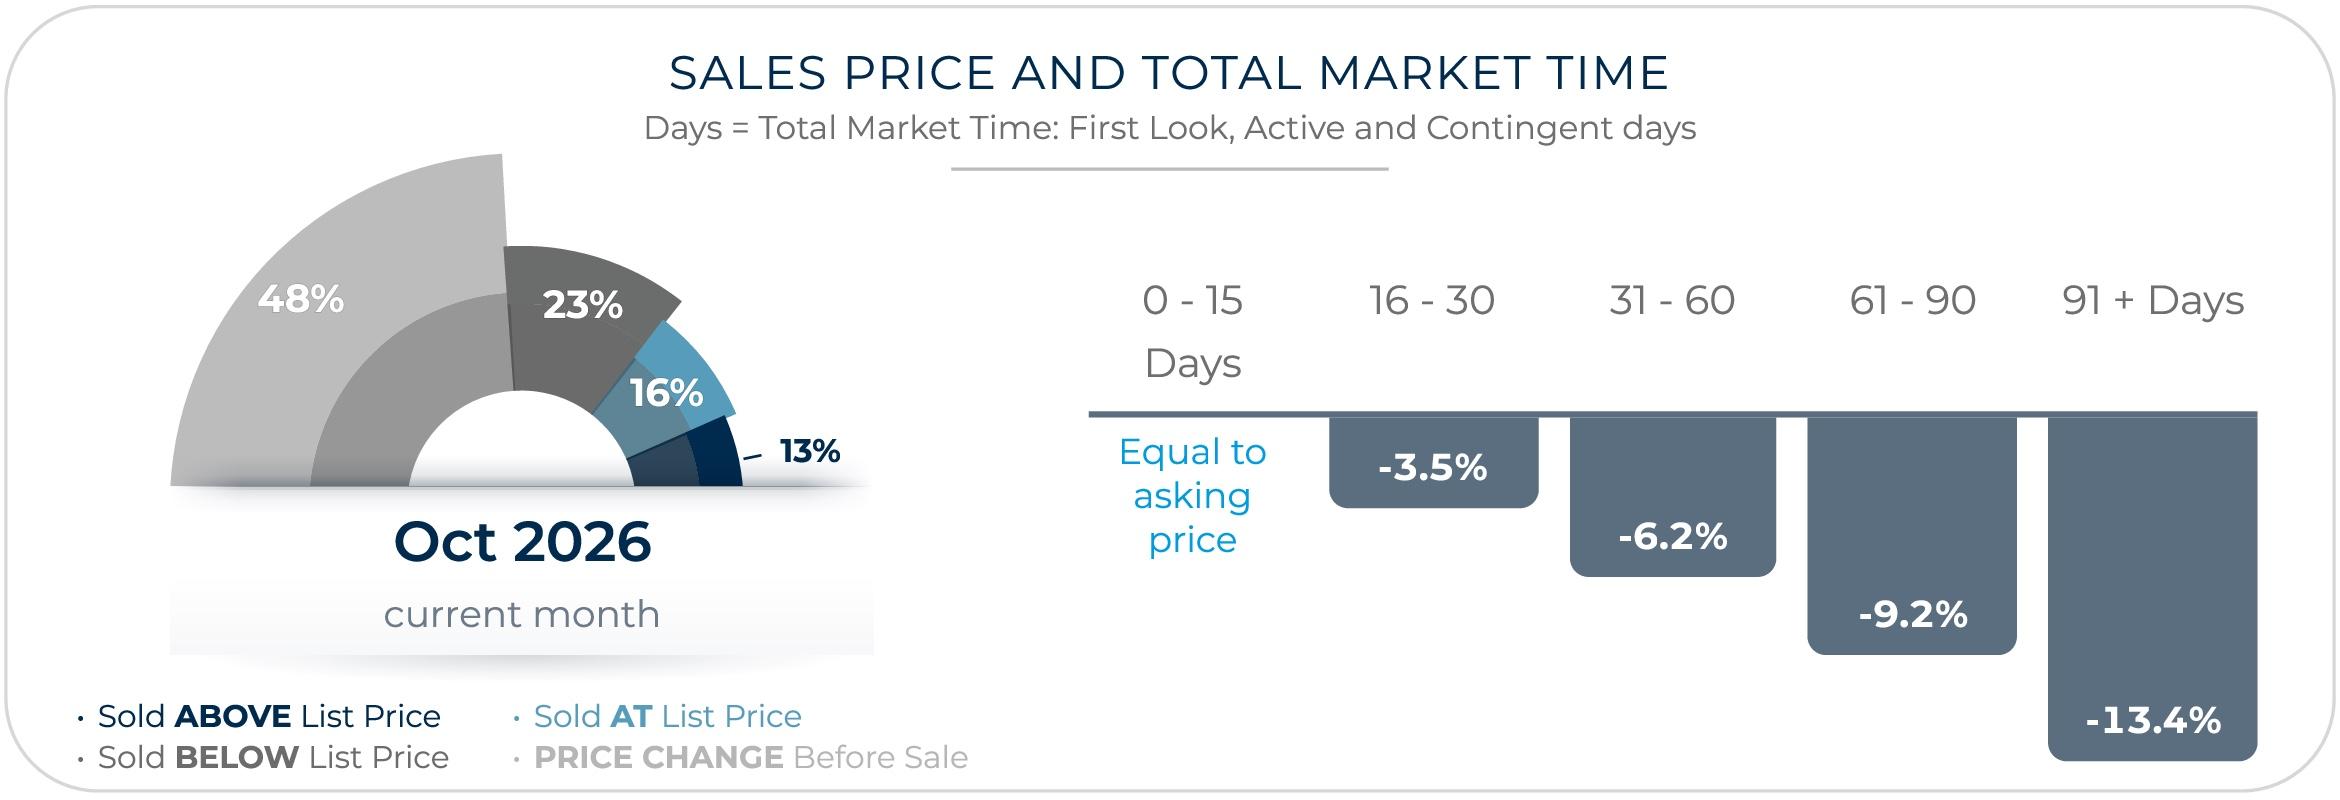
That first week is when your listing gets the most attention, from new buyers and from everyone who's been watching and waiting. Price it right, and you create urgency and maybe even competition. Price it too high, and buyers scroll past.
Also think about how you offer incentives. A 2-1 buydown on a $600,000 loan costs a seller about $14,000, but it can lower a buyer's payment by nearly $800 a month in the first year. To a buyer focused on the monthly payment, that can mean more than a $14,000 price cut.
In a market with too much inventory, being "pretty good" doesn't cut it. Your home needs to be the obvious choice. Let's talk about how to get it there.
Thinking about buying or selling? Let's talk about what makes sense for your situation.
Keep reading
- 01Seattle Housing Market Update: October 2026
- 02Seattle Housing Market Forecast 2027: What Buyers and Sellers Should Expect
- 03South Seattle Market Report: Q3 2026
- 04Seattle Housing Market Update: September 2026
- 05Seattle Housing Market Update: August 2026
- 06Seattle Housing Market Update: July 2026
- 07Seattle Housing Market Update: June 2026
- 08Seattle Housing Market Update: May 2026
- 09What is my Seattle home worth?